Monday, March 26, 2012

RSY: XXXXVII: Buy AVCA at $5.59

Advocat Inc. (AVCA) is rated as a Strong Buy by Sabrient for its excellent value and growth scores of 92.9 and 83.8 respectively (top is 100). With less than average market risk it is expected to outperform the market significantly. AVCA's accounting and governance ranks it at the top for conservative practices, which is noted by Sabrient rating AVCA at 82.5 for its Fundamental Score. Beneficial owners have been accumulating positions in this micro-cap stock. Healthcare is a sector that RSY does not have a position in and would help balance the portfolio with this 4% dividend yielding stock.

Since it is a lightly traded stock, RSY recommends buying a small position of 400 shares at a limit price of $5.59 {good for the day}. The ex-dividend date is March 28, so this is a good time to capture a position in it now.

AVCA does not have options available but reviewing our open options shows that the Jun $80 Call for ARLP is down around $0.25 from our 1 option sold at $4.10. The bad news is that ARLP has dropped in price while capturing the option premiums. ARLP is rated a Buy by Sabrient and RSY recommends continuing to hold this position and wait for better prices to sell or covered calls again.

Both TESS and BRKL do not have options available, but are priced so that we can reduce our exposure while capturing some of the capital gains. RSY recommends selling half of each position as such: Sell 200 shares of TESS at $23.01 {GTC} and Sell BRKL 200 shares at $9.51 {GTC}. Sabrient rates BRKL as a Hold presently and TESS as a Buy. This will result in a small gain in BRKL but nearly $2300 in gains from TESS on the 200 shares sold and nearly 100% in gains!


AVCA 4% AI-100% StockScouter 8 Healthcare : Healthcare Facilities
Sabrient rates AVCA a Strong Buy for its excellent value and growth scores.
Value 92.9 Growth 83.8 Sabrient Fundamental Score of 82.5

LFVN-Lifevantage Corporation

Buy!!!
OKS 4.36% 4-28-2018 of $0.61 AI-77 StockScouter 9 Utilities
Growth And Quality Don't Come Cheap At Oneok Partners
Value: A rank of 29.1 for the Sabrient Value Score implies that historical and
projected earnings are already priced into shares of ONEOK Partners.
Balance Sheet: 6.2 YUCK!!!


Sell 1/2 of
BRKL HOLD 400 shares
TESS HOLD 400 shares
No options.
Buy to cover ARLP option.

Sell NLY after April 1st
FCX??? SELL

Labels: , ,

Saturday, February 18, 2012

A Macro View: Stock Picking based on PPI Index

The recent release of the PPI index and core PPI has sparked some interest in how it is related to stock market returns. Calafia Beach Pundit thinks that the
PPI inflation Of 3.5% points to higher yields ahead.

From my regression research, the PPI index has the highest correlation with stock market returns by sector versus the CPI indexes of core and headline. Results for back-testing over the last 10 years also resulted in greater returns for the PPI over the CPI although core CPI does better than the headline CPI. But for the PPI versus core PPI, the results for the core PPI are very weak and much lower than the S&P 1500 flat weighted. Even when adding core to the headline PPI results in lower returns than just PPI.

The above regression analysis was in regards to sectors and stocks that performed well when the index was going up, that is, inflation heating up on the consumer side or the producer side also called "Lovers". This week's stock picking is based on a regression back test from July 2000 until the latest release in February for January's numbers. It performed better than the S&P 1500 flat weighted and achieved nearly 10% annualized return over the back test period. The following stock picking list is the "Lovers" list and filtered by Sabrient's Strong Buys and Buys.

Assurant, Inc.,AIZ, STRONGBUY
Peabody Energy Corporation,BTU, STRONGBUY
Nabors Industries Ltd.,NBR, STRONGBUY
Baker Hughes Incorporated,BHI, BUY
BB&T Corporation,BBT, BUY
ConocoPhillips,COP, BUY
CSX Corporation,CSX, BUY
Halliburton Company,HAL, BUY
Helmerich & Payne,HP, BUY
International Paper Company,IP, BUY
PerkinElmer,PKI, BUY
Pioneer Natural Resources Company ,PXD, BUY
SunTrust Banks,STI, BUY
Zimmer Holdings,ZMH,BUY


CARPE DIEM: U.S. Manufacturing Is Open for Business and Doing Well; Despite, Not Because of, Government Policy

CARPE DIEM: Chart of the Day: Drill, Drill, Drill = Jobs, Jobs, Jobs


Lovers:
Symbol Rating Price * Market Cap SABRIENT SCORES
Value Growth Momentum
AIZ STRONGBUY 43.97 Mid-Cap 88 33 63
BTU STRONGBUY 35.96 Large-Cap 97 65 15
NBR STRONGBUY 19.16 Large-Cap 98 86 41
BHI BUY 47.9 Large-Cap 98 83 32
BBT BUY 29.65 Large-Cap 62 59 97
COP BUY 72.81 Large-Cap 74 49 24
CSX BUY 21.94 Large-Cap 92 78 43
HAL BUY 36.14 Large-Cap 98 90 32
HP BUY 59.31 Large-Cap 78 95 53
IP BUY 33.02 Large-Cap 70 38 93
PKI BUY 26.07 Mid-Cap 44 94 78
PXD BUY 111.85 Large-Cap 18 87 71
STI BUY 22.28 Large-Cap 96 33 87
ZMH BUY 61.25 Large-Cap 54 72 70

Labels: ,

Monday, November 21, 2011

RSY: Tall TAL

Sabrient rates TAL a Strong Buy for its superior value and growth profiles, which indicates a stock that should outperform the market. TAL International Group, Inc. boasts an outstanding value growth of 80.4 (out of 100) and more outstanding is its 100 score on growth. Rigorous backtesting reveals that stocks with similar growth profiles outperform the market in the long term especially if they continue to exceed expectations. Just last month it beat consensus estimates for the 3rd quarter by 10 cents to $1.01 per share. Even though the pay out ratio is above 50%, with strong performances like last quarter, that should be a minor concern.

Underlying TAL's excellent value scores is its earnings score of 70.1 and outstanding fundamental score of 86.9. TAL's forensic accounting score is average, which indicates its level of risk going forward. With these strong fundamental scores TAL is expected to significantly outperform the market over the near term.

TAL's next ex-dividend date is coming up on November 29 with a dividend of $0.52/share. The dividend yield is a very decent 7 1/2% and each quarter the ratio is 1.85%. Adding this position will increase exposure in the services sector but unique in the rental and leasing of transporters. RSY recommends a buy limit order of TAL 400 shares at a limit price of $26.99 for tomorrow's opening (GTC). Today's market weakness will probably reverse some at the opening, but still down over a dollar from Friday's close.

Update
Since the last update, dividends provided almost $650 of gains in the model portfolio. RSY also closed out the call option on ARLP for a gain of $267 and the put option on DLX expired with a gain of $239. Below is all the transactions in the model portfolio since inception. (Click to enlarge.)


Optional Options
ALLIANCE RES PARTNER L P UT LTD PART JUN-12 $75.00 CALL @ $6.05
COMPASS DIVERSIFIED HOLDINGS SH BEN INT MAY-12 $15.00 CALL @ .75 Loss
DELUXE CORP COM APR-12 $22.50 CALL @ $3.40 <>
KRONOS WORLDWIDE INC COM MAY-12 $20.00 CALL @ $5.00
STMICROELECTRONICS N V NY REGISTRY APR-12 $7.50 CALL @ .95 -----


WSTG 11-17-2011 AI 47 SS 4 {Insiders nominal.}

TAL 11-29-2011 SS 7 AI 53 {Insiders nominal.}:

TAL International: A Terrific Company - Seeking Alpha

Yahoo! Message Boards - TAL International Group, Inc. - EPS $ .54?
They made .54 vs .38 last year after adjustments for swaps
last quarter .70 vs .17.

Cash increased recently/

Depreciation creates a non cash charge.

Dividend is .52 vs .5 last quarter and .3 last year.

Company does not foresee major recession risk or default of a major customer.

Sales increased from Dec 10 alot more than the increase in Accounts Receivable. ( Positive) -- unless I am reading something wrong?

Company expects flat to down results from this quarter with the next.

Last year 4 th quarter they made 1.15 vs op income of .76 due to gain on swaps.
TAL says flat to down next quarter pre tax op income of $1.56.
As long as Europe and the US experiences no hard landing recession, TAL's payout of .52 a share will hold up.
People sold this one off anticipating recession.

I sold out months ago at 28.5 and 27.5 but did not buy back at 23 or higher. Spooked by the macros. TAL in 08 09 ELIMINTED the div! Stock went to 9 or less.

MACRO looks better, high dividend of 7.5 % plus looks good, but don't expect much capital appreciation from this point.

Labels: ,

Sunday, August 14, 2011

RSY XXXIII: IVR

Sabrient Systems recently upgraded Invesco Mortgage Capital Inc. {IVR is a real estate investment trust (REIT)} to Strong Buy because of its outstanding value profile. IVR should be familiar with RSY portfolio watchers as it was one of the first two positions entered on August 23, 2010. The RSY portfolio had net gains of $1434 (after transaction costs) with nearly a thousand from dividends until it sold out its last lot on June 17, 2011 at the price of $20.96. Friday's price range was $18.28 to $18.90. At that time Sabrient had downgraded IVR to Sell.

IVR has average at best forensic accounting score but has greater potential to outperform the market with lower risks than most stocks at present time according to StockScouter. Insider buying continues to be strong indicator of forward growth. While Earnings Score and Balance Sheet Score is below average, the Sabrient Fundamental Score is 92.7 (out of 100), which measures a company's financial health, including its balance sheet, cash flow, revenue, and earnings quality. With a Sabrient Fundamental Score of 92.7, INVESCO MORTGAGE is substantially higher than the average of its industry group, which carries a Sabrient Fundamental Score of 55.2.

Also of most importance is that Ben Bernanke gave his word that he will continue to shower the banking industry with free money. Not really, but he did promise to keep rates low until at least 2013 as long as the economy continues to show weakness. When evaluating IVR for the portfolio in 2010, it was an issue if interest rates were going to rise, which could hurt highly leveraged firms and industries like REITs. At the time, the Macro View was looking for low interest rates for at least the length RSY was hoping to hold IVR. Now it seems reasonable again that interest rates will remain low for the foreseeable future.

When the buy was recommended last time, RSY suggested buying 400 shares. This time RSY suggests a slightly different approach. First, we want to enter a long position for some exposure on the great upside potential. RSY recommends a buy order of 200 shares of IVR at a limit price of $18.99 (GTC). Second, let us try to capture any future price "dips". RSY recommends a sell of 2 contracts of IVR Jan 21 '12 $17.50 put at a limit price of $1.60 (GTC). Once the long position is taken, looking at writing covered calls is also a possibility. At present time, none look worth the reduced upside potential as most are below even one dividend payout. RSY is expecting the next ex-dividend to be around September 15th.


Bernanke's Zero Interest Rate: What It Means for Your 401K (And What to Do About It) - Seeking Alpha

Increasing Uncertainty Continues to Overshadow Non-Agency Mortgage REITs - Seeking Alpha

Bernanke Buoys mREITs by Removing 'Extended Period' Uncertainty - Seeking Alpha

Agency mREIT Dividends the Obvious Winner After FOMC Interest Rate Announcement - Seeking Alpha


Dividend Yield Should Support Decision to Buy Invesco - Seeking Alpha

Sticking With Proven Agency-mREIT Winners Until Invesco Proves Itself - Seeking Alpha

AGR
Aggressive (30)

INVESCO MORTGAGE CAPITAL INC: STOCK RATING SUMMARY
10
StockScouter


Invesco Mortgage Capital Inc, a mid-cap growth company in the finance sector, is expected to significantly outperform the market over the next six months with less than average risk.

10 is the best possible rating.
IVR : 18.64 +0.32 +1.75% - MSN Money

Labels: ,

Monday, July 25, 2011

RSY: DLX, Optional Options

Deluxe Corporation (DLX)-- Sabrient rates DLX a Strong Buy for its solid value profile, which makes it one of the better value stocks in today's market, despite modest growth and momentum scores. The RSY portfolio loves growth at a reasonable price (GARP) stocks but value is more important versus growth rates. Weakness in the projected earnings growth gives it a low Earnings Score from Sabrient. But with a Sabrient Fundamental Score of 98.3 (which measures a company's financial health, including its balance sheet, cash flow, revenue, and earnings quality), Deluxe is significantly higher than the average of its industry group of 57.0.

According to SmartConsensus, DLX and its 5 other peers in the Commercial Printing Services industry all received a hold rating from them. Not a lot of excitement there. DLX's accounting practices are with-in an acceptable range and risk is average. As a solid value stock it should outperform the market over the longer-term and with its dividend yield of over 4%, it pays to hold this one. The middle of August should be its next ex-dividend date.

NakedValue noted that DLX was an Under-the-Radar Low P/E Dividend Paying Stock. That was the good part but then it described the earmarks of a maturing industry with margins increasing but sales decreasing. Like most companies in maturing industries, endeavors into the on-line services is one of their goals. Deluxe recently purchased Banker's Dashboard which give banks daily access to their financial position through on-line tools.

The PE ratio (TTM) is just 8.42 and forward looking it is expected to decline slightly. For a more complete analysis of Deluxe's cash flow check out Why Deluxe's Earnings Are Outstanding.

RSY recommends a buy of 200 shares of DLX at a limit price of $24.09 (GTC). This will be the first buy into the Consumer/Non-Cyclical sector and since this will be less than 5% of portfolio (based on a portfolio of $100,000), RSY also suggests to sell two put contracts of DLX of the Oct 22 '11 at $22.50 at a limit price of $1.25 (GTC).

Juice up Returns with Options.
Let us see if we can juice up the returns with some covered calls on our long positions. RSY presently holds a covered call of Foot Locker Jan '12 at $22.50 which is working out so far. Since RSY diversified across caps including some micro-cap and small-cap stocks, not all long positions have options available or have such shallow trading that it might not be worth the trouble such as BRKL. RSY recommends the following to consider:
1. Alliance Resource Partners (ARLP) Mar 17 '12 $80 Call, 1 option contract at limit price of $5.
2. Compass Diversified Holdings (CODI) Feb 18 '12 $17.50 Call, 2 option contracts at limit price of $0.50.
3. TOTAL S.A. (TOT) Feb 18 '12 $60 Call, 1 option contract at limit price of $2.40.


EV/EBITDA

Checks and Services for Small Business, Banks, and Credit Unions - Deluxe Corp

DELUXE CORP: STOCK RATING SUMMARY StockScouter Rating: 9
Deluxe Corp, a small-cap value company in the consumer services sector, is expected to significantly outperform the market over the next six months with average risk.


The Advantage of Monthly Dividends Over Quarterly Dividends - Seeking Alpha

Smaller unit helps Deluxe post 4% sales gain - Seeking Alpha


Deluxe Corporation (NYSE:DLX)
Industry: Commercial Printing Services
Market Cap: $ 1,269.5mm (Mid Cap)

AGR
Average (48)
*********************
P/E (Trailing 12 mo.) 8.42x
EPS (Trailing 12 mo.) 2.946
Next Earnings Date 7/28/11
Market Cap 1.3 B
Shares Outstanding 51.4 M
Beta 2.0
Dividend Yield 4.08%
Declared Dividend 0.250
Ex-Dividend Date 5/19/11
Dividend Payable Date 6/6/11

(2) A non-binding resolution on executive compensation (or "say-on-pay vote"):

For: 34,792,130

Against: 1,690,330

Abstain: 129,725

Broker non-vote: 5,872,797

(3) A non-binding, advisory vote on the frequency with which we should conduct

future say-on-pay votes:

One year: 30,143,352

Two years: 308,412

Three years: 6,029,103

Abstain: 131,318

Broker non-vote: 5,872,797

Based on a determination of our Board of Directors in light of these

shareholder voting results, the Company has decided to conduct say-on-pay votes

every one year, until such time as our shareholders are next asked for an

advisory vote on the frequency of conducting future say-on-pay votes.


SmartConsensus Peer Ratings Detail:
6 holds; 90days ago: 3,3,1; 1 year ago: 2,2,1.

Labels: ,

Thursday, June 30, 2011

RSY XXXX: Sell 1/2 Total, Buy FNLC

Although, just recently I put my eye on Pulaski Financial Corp. (PULB), I like what I see. One very positive signal to start with is that insider buying is greater than selling with 17 transactions of insiders buying to one selling according to Yahoo Finance (at PULB Insider Transactions), and number of shares is nearly 5 buying to one selling. On forensic accounting scores, PULB scores acceptable with a near "conservative" rating. They did have one issue with a late filing in May 2010, but since that time no major issues have arisen. Sabrient Systems has this to say on the SmartStock Reports:
Sabrient Analysis
PULB is rated a Strong Buy for its outstanding profile as a value stock, combined
with strong growth attributes.
• Value: A Sabrient Value Score of 89.4 indicates that PULB's stock price does not
fully reflect recent and projected earnings results. This implies that the stock holds considerable potential for price gain together with reduced downside risk.
• Growth: A Sabrient Growth Score of 77.8 suggests the stock has good potential as
a growth stock.
Another fine GARP (Growth At a Reasonable Price) stock that should be well suited for long-term value investors. In addition to our all important value score and good growth potentials, PULB also shows outstanding Balance Sheet Score (measure of comapany's liquidity and debt issues) of 92.6 and Fundamental Score (broad measure of a company's financial health) of 90.5 (out of 100 scores).

The next question becomes how many shares will enhance the RSY portfolio for the long-run. This is a good time to look at our portfolio and compare the percentage holdings of each position as well as sectors. The table below shows the current holdings of the RSY and their respective percentages of the total portfolio which includes the cash on hand.

RSY recently added FNLC which is another regional bank like PULB. Since RSY has over 8% in financial sectors, and PULB is a micro-cap stock, RSY recommends a purchase of 400 shares of PULB at a limit price of $7.19. Good-til-close is recommended but if it does not trade by the close of July 5th then close the order as the ex-dividend date is July 6th.

The table also shows a concentration of stocks in energy with over 18% of the portfolio. TOT is still rated a buy by Sabrient. Since the next ex-dividend date is in November and we just got $1.61 per share on June 17th, RSY recommends a sell order of the last lot purchased of TOT for a small gain and hold the other half for now. RSY recommends a sell of 100 shares of TOT at a limit price of $57.51 (GTC).

Labels: ,

Tuesday, June 21, 2011

RSY XXXIX: Buy FNLC

Last month, I was Questioning the QE Monetary Transmission Mechanism, and used MyStockFinder tool to find a selection of GARP regional bank stocks. Today, I want to look at one in particular, First Bancorp, Inc.(FNLC).

FNLC shows plenty of attributes we look for in a value, dividend portfolio. Some of the most appealing are: good insider buying by directors, a near perfect forensic accounting score, and most importantly a good dividend yield of nearly 5 1/2. Sabrient Systems states the following about its buy rating of FNLC:
FNLC's exceptional value profile earns it a Buy rating.
• Value: With a Sabrient Value Score of 84.6, FNLC is one of the more desirable stocks with regard to valuation. At its current price, the stock is a superior candidate for value-minded investors who seek high potential gains with low downside risk.

In addition to the good Value Score, it boast above average Earnings and Balance Sheet Scores and an exceptional Fundamental Score of 81.7. The Sabrient Fundamental Score is the broad measure of a company's financial health, including its balance sheet, cash flow, revenue, and earnings quality.
"We continue to post good earnings and our capital ratios remain strong," stated Daniel R. Daigneault, the Company's President & Chief Executive Officer. "Many of our shareholders invest in The First Bancorp because of our generous dividend, and good earnings and strong capital are the two major factors enabling us to maintain the ability to pay dividends at this level."

Certainly music to our ears as they declared a dividend for July 1st ex-dividend date of 19 1/2 cents per share.

RSY recommends a buy order of 400 shares at a limit price of $14.41 (GTC-close before end of month).

Labels: ,

Monday, May 23, 2011

RSY XXXVII: No More Gas {EGAS}

Sabrient downgraded EGAS to Sell and thus RSY recommends unloading the remainder of the holdings. Sabrient's analysis states that, "EGAS's weak showing for Sabrient's key growth and momentum measures earns it a Sell rating." Those are troublesome enough facts but also EGAS's Earnings Score and Balance Sheet Score are subpar. RSY recommended opening an initial position of 400 shares based on a $100,000 portfolio on November 15th, and then recommended unloading half on January 13th. RSY suggests placing a sell limit order of the 200 remaining shares of EGAS at $11.19 (GTC) at the opening bell. That should net us a couple of hundred of capital gains for this transaction and around $111 for the last sell and $72 in dividends including the one scheduled for distribution at the end of the month.

Labels: ,

Sunday, May 15, 2011

QEII: The Hyperinflationistas United for the Revolution!

Questioning the Quantitative Easing Monetary Transmission Mechanism or something like that...

A lot of attributes have been assigned to the actions of the Fed, especially with regard to their policy of Quantitative Easing (QE), including but not limited to the rise in commodity prices worldwide, equity markets taking off, worldwide inflation especially in lower income countries, decline in the value of the dollar, domestic inflation rising, and finally reaching the ultimate in a misery index with stagflation. But in all the theories I have read about, there is no mention as to how the money gets from the Fed to the various markets. This might be called the monetary transmission mechanism as Ben Bernanke wrote about in 1995 in a paper entitled Inside the Black Box: The Credit Channel of Monetary Policy Transmission.

Less formally we could at least say how QE transfers the money from a commercial bank to either highly volatile assets like commodities and stocks to simply speculative instruments like futures and derivatives. We do know that the first transfer is that the Fed purchases long-term financial instruments especially government bonds. But then what happens? Do the bankers hand it over to their cousin Vinny to go bet at the Merc? That seems highly unlikely.

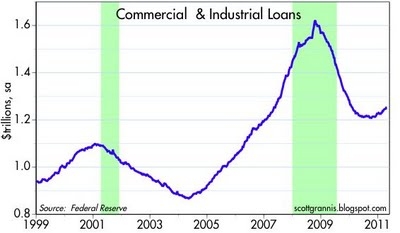
Even if there is More Good News as Bank Lending Continues to Rise, that is still a leap to confirm that the monies are ending up in the hands of speculators or investors in the stock markets.

The fact that Commercial and Industrial Loans are increasing at an 8.6 annualized rate is certainly good news for the economy overall. The important question here is where does the money go after the Fed exchanges cash/money for the government bonds? The last phase of quantitative easing dubbed QE2 started in the later part of 2010 and was officially announced in the early part of November. (Graph: Excess Reserves of Depository Institutions (EXCRESNS))

That graph certainly shows a huge increase in reserves since QE2 came about and in the same magnitude of the total amount of QE2 at around $600 billion. Since the first QE started in late 2008 let us look at a longer term graph.

That is probably not every dollar put into the system from QE1 and QE2, but the rise from near zero to over 14,000 billions (1.4 Trillion!!!) of excess reserves covers the majority of the easing as reported. So what are these reserves doing there if not lent out to prospective borrowers? (Interest Rate Paid on Excess Reserve Balances)

I honestly can not answer why the Fed is paying interest on excess reserve balances. But one thing is clear, quantitative easing is mostly or completely absorbed by the excess reserves, thus it is not a monetary transmission mechanism that is causing some markets to expand.

What is the Transmission Mechanism Then?
The most logical transmission is not a transmission of monies but just a simple change in expectations. If prices are to rise in the future then selling in the future is a better option and interest rates will need to rise accordingly now.

Cullen Roche that blogs at Seeking Alpha provides some cogent discussions about QE2. Commodities react almost instantaneously to new information and adapt accordingly, and at "Fed Contributing Directly to Speculative Behavior" he shows how the commodity prices spiked over the Fed Chief’s press conference. Even though he thinks that QE2 was mostly a flop, he states that "A QE3 Would Only Exacerbate Commodities Speculation, Further Curtailing Real GDP Growth". He may have a point going forward and his biggest complaint about QE2 was that it targeted the amount of transactions and not an explicit interest rate target as normal monetary policy is pursued. In other words, long-term bond rates should have been targeted and amount of transactions ignored which would use more of a signaling to the markets than specific transactions in the market.

Hyperinflationistas...
While most of the recent events can be explained by rising corporate earnings or simply supply and demand, I can not help to think that some of the Inflationistas and Hyperinflationistas took their own advice by buying up commodities and investing more in equity markets. The investments in the stock markets is overall a good thing. Commodities might be pushed higher from this frenzied buying, which could in fact create the necessary political will to reduce the structural rigidity this blog has been talking about. And sure enough with gas costs high, Obama to speed oil production.


Why QE2 Was Hardly a 'Non-Event' - Seeking Alpha

The Bond Market's Inflation-Forecasting Abilities - Seeking Alpha

Bank Lending Update: Economic Building Blocks Start Stacking Up - Seeking Alpha

http://krugman.blogs.nytimes.com/2011/05/15/money-1937-slightly-wonkish/

Impact of Fed Stimulus Debated

Federally Funded Friday - Bernanke Says More Free Money! - Seeking Alpha

GDPhursday - Reality Check - How Much is that Priced in Euros? - Philip Davis - Seeking Alpha

The Bernank Says He Is Responsible For Higher Stocks Not Higher Commodity Prices - InTheMoneyStocks.com - Seeking Alpha

The Transmission Mechanism for Quantitative Easing (Wonkish) - NYTimes.com


Quantitative easing and the commodity markets | The Great Debate

Analysis: Fed's QE2 raises alarm of commodity bubble | Reuters

POMO Thursday: Bernanke Serves Up Another Round - Seeking Alpha


Reserves - FRED - St. Louis Fed

Graph: Excess Reserves of Depository Institutions (EXCRESNS) - FRED - St. Louis Fed

FRED Graph - St. Louis Fed

Interest Rate Paid on Excess Reserve Balances (Institutions with 2-Week Maintenance Period) (INTEXC2) - FRED - St. Louis Fed

Excess reserves - Wikipedia, the free encyclopedia

The Fed initially announced a $600 billion program in November 2008, but then four months later, increased that to $1.8 trillion, when it wasn't enough.

QE1: Nov. 2008-June 2010
QE2: Nov. 2010-June 2011 (estimation)


From RDRutherford:
QE2's Failure and the Housing Market - Seeking Alpha


An Event Study on the Fed and QE2 - Seeking Alpha

The Impact of the Fed's Stimulus Is Debated - Seeking Alpha
Impact of Fed Stimulus Debated


Fed Survey: Big Banks Ease Lending Standards - Real Time Economics - WSJ
Quote:
�The most often cited reason for stronger demand noted by larger banks was greater demand for financing merger and acquisition activity,� the Fed said.

Banks, citing increased competition, eased standards on commercial and industrial loans. �Some banks that had eased standards and terms also pointed to a more favorable or less uncertain economic outlook,� the Fed said.

Demand for commercial real-estate loans also increased, the Fed said.


Structural Rigidity: War, Counterror Act Like Sand in Economic Gears - Real Time Economics - WSJ

Calculated Risk: Fed: Banks more willing to make consumer loans

Fed�s Hoenig: Rates Should Start Rising - Real Time Economics - WSJ

Fed�s Rosengren Says Recovery Weak, Policy Just Right - Real Time Economics - WSJ

The Fed's Language Problem on Inflation - NYTimes.com

Labels: ,

Tuesday, May 10, 2011

RSY XXXV: Optional Options

Just as selling into a strong market is good, selling covered options in a strong bull run is beneficial. Before we look into some possible choices for selling covered calls on our portfolio, let us look at the latest Sabrient ratings for our rated positions.

Since there is no rush to unload any specific position, RSY portfolio would like to pick longer term contracts to make it worthwhile. Some of the positions do not have options available. Just like the adage says to make money by selling high and buying low, we want to pick out options to sell that are above their theoretical value and buy back below their theoretical value. RSY rejected Total (TOT) for that reason.

Just as RSY recommends good-til-cancelled (GTC) limit orders for buys and sells, RSY suggests the same for option orders. Some of the possible options that could be fruitful are:
1. STMICROELECTRONICS (STM) OCT-11 $12.50 CALL, 6 option contracts at limit price of $1.20.
2. FOOT LOCKER INC COM (FL) JAN-12 $22.50 CALL, 2 option contracts at a limit price of $2.45.
3. COMPASS DIVERSIFIED HOLDINGS (CODI) NOV-11 $17.50 CALL, 2 option contracts at a limit price of $0.75.
4. INVESCO MORTGAGE CAPITAL (IVR) OCT-11 $30.00 CALL, 2 option contracts at a limit price ofoption contracts at a limit price of $0.45.

Labels: ,

Wednesday, March 30, 2011

RSY XXXII: No COP needed now but order TOTal

After the RSY success in its position of LZ, I wanted to get back into the same or a related sector and industry. Current events have shown the need for energy and chemical production for worldwide economic growth and the rebuilding of Japan including petcoke which the US supplies to Japan.

I first used a modified RSY in MyStockFinder with only the Basic Industries checked for sectors. Nothing got me excited enough to recommend. I then expanded the search for Basic Industries and Energy sectors with only Strong Buys. As the title said, COP {ConocoPhillips} was a close contender for adding to the RSY, but I think that TOT {TOTAL S.A.} provides a better choice for now. In addition to having strong chemical divisions that would replace the LZ chemical position, it also provides a better dividend of over 5% dividend yield compared to COP with around 3 1/4%. TOT already has declared a nice dividend of $1.577 for May 18th.

Both COP and TOT have exposures to Libya and if Qaddafi stays in power this could hurt Western oil companies. COP was already thinking about exiting from Libya, Nigeria and 3 other countries. According to the article 5 Best Positive Cash-Flow Oil Companies, TOT has 2.6% exposure of revenue and COP was at 3.3%.

As my last post mentioned, this uncertainty to recent world events {especially Libya} provides opportunities. Here, oil companies could benefit from a freer and more open society. The Economist magazine recently suggested the "West should recognise the council {interim national council} as a traditional government provided that it promises to hold multiparty elections." Even if Qaddafi stays in power in the west, the majority of oil production is in the East and a split Libya could provide opportunities for production also even in a civil war situation.

RSY recommends a limit buy order of 100 shares of TOT at a limit price of $60.91 {GTC} for the opening on March 31st.

Update: TOT gaped up and never hit our price target. RSY recommends raising the limit order to $61.11.

Labels: ,

Thursday, March 17, 2011

RSY XXX: Buffett makes a call, Unload LZ. Buy DLN 200 @ $47.01

The events in Japan has shown that there are always risks and uncertainties in any investment. Just think what the value of time-share condos at Ōkuma near the Fukushima Dai-ichi Nuclear Power Plant is about now. While insurance can compensate individuals for these risks and uncertainties, they do not negate the costs to society when tragedies do occur. And of course no costs can be completely analyzed without understanding the full extent of human lives lost and the damaged/destroyed lives of the survivors.

Along with the risks associated with any tragedy, they also provide opportunities as the economy changes to adapt to new demand structures. One area that could be lucrative potentially, as Japan reconstructs much of their coastal cities, is commodities and basic materials. With the nuclear industry getting hit on all sides then it is logical that our holdings of ARLP is doing nicely since March 11.

Irregardless of the timing, Berkshire Hathaway has decided to purchase our holding of LZ for cash of $135.00 per share. If you held it long, without writing a covered call, it certainly seems to be the time to unload with a large capital gain now. Interest rates being low then the arbitragers have narrowed the gap between offer price and market price to as low as 70 cents difference. Not withstanding the ambulance chasers and their delusional investors (Law Office of Joseph Klein, Faruqi & Faruqi, Law Offices of Vincent Wong, Ryan & Maniskas, Law Offices of Howard G. Smith, Law Office of Abe Shainberg, etc.), most recognize this as a solid deal that is not likely to be adjusted up or to fall apart. That is, investors are not bidding above the offer price as it did at times with other mergers, and shorts are backing off of it also as recognized by Kapitall at 20 Stocks Seeing Unusually High Trading Volume, Decreasing Shorts. S&P also recognized the value as being close to realistic as they downgraded LZ from a Buy to a Hold.

Forgive my ranting, but if investors really thought that LZ was worth $148/share (as Thompson/First Call stated) then there is no way any rational investor would allow it to drop to below $104 last Friday, March 11th. Any rational investor seeing a discount of nearly 30% should jump at the chance as soon as possible with as much gusto as possible.

Selling the covered call has limited our upside potential, but during the down days it limited our losses and for that it was good. Now we need to unwind our trades while maintaining the gains as much as possible. Along with the decreased interest by the short players, option players have dropped the price so that the time value of the options are nearly zero. When RSY recommended the sell of the covered call, the theoretical value was below what we sold it for and now the selling price is about half the theoretical value at $30.86. The JUN-11 $120.00 CALL has been trading in the $14.10 to as high as $15.80. So the plan is to enter a buy to cover, limit order at a price of $14.10 which signifies a loss of around $5.50 per share before transaction costs. As soon as that trades, RSY recommends a sell of LZ at a limit price of $134.01 or whatever seems reasonable at the time. Good luck.

Even before this recent spat of selling for the RSY portfolio, we were looking to find ways to diversify our holdings across market caps and segments of the economy. One way is to use ETFs since they are a basket of equities. They are much more diversified than individual investors normally get that hold stocks of independent companies. For our Silver Level subscribers, we offer ETF Ratings Reports on hundreds of ETFs. Two that are promising candidates are LargeCap Dividend Fund (DLN) and Total Dividend Fund (DTD) both provided by WisdomTree, and both are rated by Sabrient as Attractive with a score of 69 and 59 respectively. Taking a look at the chart below for DLN of sector concentrations, we see a fairly well diversified portfolio to start with.

This fund is underexposed to three sectors: Basic Industries, Consumer Durables, and Transportation. While being somewhat diversified across sectors, there are also some gaps here. On the other hand, this fund is not overexposed to any particular sector and is therefore not unduly weighted toward any particular segment of the economy. While this fund is not significantly overexposed to any particular sector, it does have some sectors that are underrepresented in its holdings. This means that there is a degree of sector based diversification, but also some expectation of increased risk due to the missing components.

The passage above was from the DLN ETF report about diversification. This does provide areas that we may want to get more exposure in especially the basic industries. Not mentioned above, but important for RSY is that both ETFs are more weighted toward "mega caps" with more exposure to quality blue chip stocks. This should contrast nicely with Sabrient's emphasis on small-cap and mid-cap choices so far for RSY.

RSY recommends a buy order of 200 shares of DLN at a limit price of $47.01 (good for the day).


Did Buffett Overpay for Lubrizol?


Investors Finally Taking Note of Contagion From Japan

Market Tumbles on Misplaced Japan Fears

What the Japanese Quake Means for Stocks

Labels: ,

Tuesday, February 22, 2011

RSY XXVIII: Sell MRH

Lots of geopolitical activity has been driving the markets lately, including whether the man with many names (Muammar al-Gaddafi) has finally lived past his sell by date as an authoritarian dictator. His thoughts seem to be more along the lines of: Do not go gentle into that good night. Recent events did affect our returns today as shown below. (Click on tables for clearer images.)

Our last post recommended a sell of 200 (out of the original 400) shares of FL and the market opened on February 1st at $18.00. This resulted in a loss of almost $250 (including transaction costs). Since that time it has hit highs above $19.50. CODI has taken it on the chin after a downgrade which was incorrectly reported by Dow Jones Newswires as an upgrade and the CEO, Joe Massoud, was taking a leave of absence. Massoud was highly praised by investors but if management is broad and deep then this should be a minor setback to a solid performing company. Just last month, Steven Kiel was praising Massoud's abilities at My Top (Relatively Safe) Holdings. In addition to the recorded loss, RSY noted the following dividend payments of: EGAS providing $18 dividend, GAIN providing $8 dividend, and ARLP providing $86 dividend. Below is a summary of transactions since inception.


RSY has been sitting on a full 400 shares of MRH since September 17, 2010. Sabrient has downgraded it to hold, and as such, RSY recommends a sell of MRH of 200 shares at $20.31. It never is good to be selling into a weak market but this seems to be the time to partially harvest some of our spectacular returns. It closed today at $20.35, so this should leave some leeway from the oversold position today, but investors should monitor this closely tomorrow morning.

Labels: ,

Sunday, January 30, 2011

RSY XXVII: Update, Sell FL 200 @ $17.89

Let us update some of the cash transactions since our post on January 12th. On the 13th, Alliance Resource Partners (ARLP) dipped down to $70 at the opening bell (The RSY portfolio recorded the buy as 100 shares at $70 exactly.) but has since dropped to below $62.50 on January 20th. Most of this drop has been attributed to a short mine closer by Warrior Mine which is a wholly-owned subsidiary of ARLP. Given that all operations are back to normal and Sabrient still has ARLP as a Strong Buy, RSY recommends to continue to hold this position. Obviously there was an opportunity to "buy on the dips" -- or dives, but to maintain a balanced portfolio RSY did not consider this move. Today, it hit a high of over $72 but settled back to $70.25, slightly over entry price.

The bright side of the portfolio is our continuous stream of dividends. As the chart below shows, RSY recorded dividends of $40 for MRH, $194 for IVR, $60 for FL and $68 for CODI, for a total of $362. I added the two right most columns to show the number of stocks in the transactions and prices of the dividend per share. (Click on tables for clearer images.)


No lumps of coal to sell, but time to sell some of our smelly sneakers.
Foot Locker (FL) has been downgraded to a hold by Sabrient. Just like when other ratings changes are dropped to hold, RSY recommended a reduction in exposure. RSY recommends a limit order sell of 200 shares (out of the original 400) at $17.89 (GTC). This will result in a loss of around $250. And now for a look at the current holdings:

Labels: ,

Wednesday, January 12, 2011

RSY XXV: Less (e)Gas and more Lumps of Coal in the Stockings.

Gas Natural Inc. (EGAS) has been downgraded to hold by Sabrient Systems and today was its latest monthly ex-dividend date. As such, let us take a little bit of profits from our position at the opening bell tomorrow. There looks to be some upward constraint above the $10.60 mark and thus RSY recommends to sell 200 shares of EGAS (half of the 400 position) at a limit price of $10.59 {GTC}. We should also note that NGPC provided us a dividend of $36.00 from our 200 shares on the 7th of this month.

If you didn't get a lump of coal in your stockings, then maybe buying some coal is a good idea now. Alliance Resource Partners, L.P (ARLP) supplies coal predominantly to utilities (91.8%) and the rest for industrial users in the US. The Motley Fool noted that they Always Raise Their Dividend. I find it more important that regular dividends are paid consistently than insistence on having the dividends increase every time but it certainly is a positive aspect of this stock. ARLP's accounting practices are quite good with a high forensic accounting score. Kapitall noted that ARLP is a company with Conservative Accounting Practices.

On the macro side of the equation, coal does not seem to have as many problems as it did a few years ago. One reason that I shorted RAIL back then. With unemployment high, the attention to pollution from coal has taken a back seat. The BP oil blowout did not help oil drilling and production here, and thus conversely electricity companies will continue to rely on coal for the foreseeable future. The Macro View of the economy has picked up and thus energy consumption will be part of this increased demand including commodities. Paul Whitfield thinks that ARLP is too thinly traded, but overall rates it and its partner Alliance Holdings (AHGP) as excellent choices.

This stock has options available for it. RSY recommends a buy of 100 shares of ARLP at a limit price of $70.39 {GTC}. The recommended moves today reduces the share of natural gas utilities and increases exposure in the production of energy...dirty coal industry.

Misc. Links:
Alliance Resource Partners: Coal and Dividends Are a Good Mix

Steelmakers expect prices to rise with Australian floodwaters

Australian Flood a Boon to US Producers?

Retiring Soon? Here Are 3 Stellar Dividend Picks

Six Consumer Stocks Paying Sustainable Dividends to Own in 2011 - Seeking Alpha

The Most Outstanding Dividend Portfolio I Know

Labels: ,

Monday, December 20, 2010

RSY XXIII: Sell TSH, LZ Dividend

Not much activity for the month of December in the RSY portfolio. Could almost say it is starting to be a lazy portfolio. LZ did provide a dividend of $36 for the 100 shares of LZ which was recorded on December 10th. RSY has not yet found another stock to add to the portfolio.

As mentioned in the last post of RSY, we should exit out of TSH gracefully, especially considering this is a lightly traded micro-cap stock. Given that it has been topping over $33 to $33.25 for brief periods, we should be able to exit at $32.99 if we are patient enough. RSY recommends a Sell 100 shares of TSH at a limit price of $32.99 {GTC}.

Also worth noting is that IVR, MRH, and NGPC all have their next ex-dividend date on the 29th of this month, and as such any further recommended rebalancing will probably occur after the first of the year. CODI shows some weakness in the charts, but RSY is still recommending a hold on the current 200 shares.

Labels: ,

Tuesday, December 07, 2010

RSY XXII: Sabrient's Ratings Review

The RSY portfolio selection and re-balancing is based on Sabrient's ratings of stocks. We also use qualitative factors to help pick which stocks and when to make trades. Thus we need to keep a watchful eye on the change in ratings for the stocks that are in the portfolio especially if Sabrient downgrades a stock to Hold and then more importantly to Sell or StrongSell. Bellow is a summary output of the RSY portfolio using the Stock Ratings Reports product from Sabrient.

This does not include GAIN or NGPC as this was dropped from Sabrient's ratings. GAIN has gone up since we took some partial gains and continues to provide dividends on a monthly basis. NGPC has dropped some, since then, but still represents a substantial gain over the entry price. It also should be providing a dividend by months end. At that time RSY may wish to exit the position if the stock charts still look negative.

FL, LZ and MRH are rated as StrongBuys and thus will maintain their recommended positions in the portfolio. If EGAS drops to a hold then RSY may consider reducing the size of holdings, but until then it will maintain its current recommendations. IVR is another that should be providing a substantial dividend by end of the month. RSY recommended a trade that netted $386 on the 200 shares sold, and is sitting on nearly 600 in gains currently. Thus, until the next ex-dividend date comes, RSY recommends a hold of the remaining shares.

Sabrient is screaming to sell the TSH position, but with a declared ex-dividend date of December 15th, RSY also recommends a hold at least until the 16th. Even given that RSY provided no recommended sells yet, an individual investor must weigh all the facts to determine his/her own investment decisions.

Labels: ,

Thursday, December 02, 2010

RSY XXI: Buy 400 FL at $19.29; Portfolio Update.

Foot Locker Inc. (FL) is rated a StrongBuy by Sabrient for its "top momentum score {92}, along with a solid growth profile {67.6}". It also boasts an outstanding Timeliness Score of 97 and a good Earnings Score of 81.7 which measures "overall earnings performance and projected outlook". The forensic accounting score is good overall and nothing negative about the insider buying or selling. Going forward, earnings estimates are expected to steadily increase over the next 4 years along with top line revenues. Cash flow per share is expected to be soft next year but certainly enough to pay out the steady flow of dividends. The dividend yield is a little over 3% which is acceptable for the RSY portfolio, and the next ex-dividend date has been announced for January 12, 2011. For diversification of the portfolio, picking FL also gets RSY into the retail industry. RSY recommends a buy order of 400 shares at a limit price of $19.29 which is close to the daily high and was the closing price. As long as there are no gap-ups at the opening, then we should be fine at this price point.

Update of Portfolio:
RSY is recording a dividend of $8.00 on December 1st from GAIN for the 200 shares held in the model portfolio. Below is a summation of trades along with the gains (or losses) of the model portfolio. (Click on tables for clearer images.)


The next table shows the current recommended holdings in the RSY model portfolio.


Top 15 Stocks Hitting New Highs, But Being Sold by the Smart Money,by: Kapitall,MRH

Labels: ,

Friday, November 19, 2010

RSY XX: Buy 100 TSH @ $32.01

Teche Holding Company (AMEX: TSH) is a regional savings bank located in Louisiana, and is rated as a Strong Buy by Sabrient for its outstanding value profile. Its Sabrient fundamental score (financial health) ranks it "substantially higher than the average of its industry group". Even more outstanding, for the aspects the RSY portfolio is looking for, is its consistent dividend payouts for over 10 years, its outstanding forensic accounting scores, and its healthy insider buying. This would be another financial sector stock but would provide exposure into the banking side of the sector. A sector that will be vital if the US is to get back to a full employment economy. The one area that is of most concern is that TSH is a lightly traded micro-cap stock. Part of the reason for low daily volume is due to a lot of "insider" ownership and low turnover rating for the largest owners, including mutual funds. The positive aspect of picking Strong Buy rated micro-cap stocks by Sabrient is their overall performance as a group compared to a comparable benchmark. At the link
Performance: Long Rankings, it shows how micro-cap stocks perform across a variety of investing styles with some of the best performance in micro-caps. Thus RSY recommends a buy order of 100 shares of TSH at a limit price of $32.01 (GTC).


With the Right Dividend Stocks, How Much Money Would You Really Need to Retire? -- Seeking Alpha


ETFs???: NFO {60}, PFM {52}, PID {57}, DLN {63}.
http://www.sabrient.com/clientarea/etf_pdfaccess.php/DLN.pdf

Labels: ,

Wednesday, November 17, 2010

RSY XIX: Update.

It seems about time to review the current holdings of the RSY portfolio and to review the transactions to date including profits {or losses}. The first table is of the current holdings of the RSY model portfolio. (Click on tables for clearer images.)


Some of the gains reported earlier have been "harvested" already. The biggest gainer so far has been MRH. Since Sabrient is continuing to rate MRH as a Strong Buy, RSY recommends holding this until the ratings changes. Thus RSY has no set target for the price and will let the winners ride. But the real proof of the pudding is in how much is the realized gains. Below is a summation of trades along with the gains {or losses} of the model portfolio.

On the 16th, RSY recommended a sell of IVR at a limit price of $22.41. From nearly the moment it opened it dropped below our limit price but on the 17th it hit as high as $22.45. I find the graph on the 17th most interesting.

It is easy to see that for all the times that IVR approached $22.45, it never got over it and the day high was $22.45. It seems obvious that someone was selling a significant amount at the limit price. It might limit our upside potential, if this pattern persists.

Labels: ,